
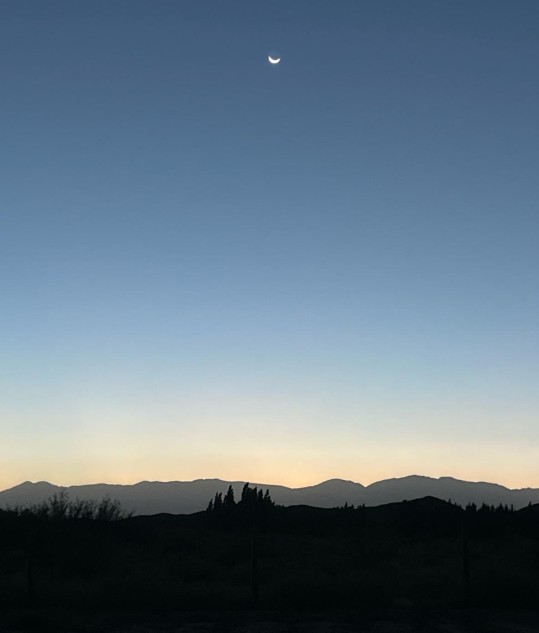
I am currently in Argentina’s San Juan Province, bordered to the west by the towering Andes. Although its GDP per capita is below the national average, San Juan hosts most of the country’s major copper development projects. Just four of these megaprojects would require well over US$20 billion in combined upfront capital investment.
If developed into producing mines, these projects could transform San Juan’s economic fortunes over the coming decades, much as mining has helped reshape the economy of Salta Province, my next port of call.
In the Weekly Market Digest, higher real rates were driven by persistent inflation, suggesting the US Federal Reserve is more likely to raise its benchmark interest rates before the end of the year.
As higher real rates imply a higher holding cost for precious metals, gold and silver prices declined, as did the equities linked to them. Industrial metals such as copper pulled back amid a rising US dollar, which continues to reach new 52-week highs.
Amid volatile market conditions, I have emphasized holding non-cash-flowing junior companies with healthy working capital positions to generate the catalysts we are focused on to drive value.
The Exploration Insights portfolio was down last week but outperformed precious metals and the equity ETF benchmarks. The performance was dragged down by a nickel-copper producer/developer/explorer in Minnesota and Michigan and a pair of leveraged precious metal developers.
In Stock Talk, a prospect generator in Eastern Europe reports a mixed bag of news. I cover drilling updates from a precious metal developer in northwest Argentina and Australia, along with a grassroots explorer in Sweden.


 Sign up for our mailing list to receive the free Speculator's Checklist for Investing in Junior Mining report right away. Occasionally, we will also send you emails with links to interviews, articles, and more.